Sacheerome: A plant at 124%, and a new one that keeps slipping
 Micro cap
Fragrances and flavours
13 September 2026 · 31 min read · Part 1: 2 min · By Pranami Hayaran
What the company does
Sacheerome makes the fragrances that go into soaps, detergents, deodorants and incense sticks, and a smaller line of flavours for sweets and drinks, to order for consumer-product companies. Fragrance was ₹143.5 crore of FY26 revenue, 94.2%; revenue was ₹152.4 crore and profit ₹28.4 crore. It has 1 factory, in Okhla in Delhi, 173 permanent staff and a second plant at YEIDA on the Yamuna Expressway that began trial runs in September 2026. It listed on NSE's SME platform in June 2025 at ₹102 a share. The promoter is Manoj Arora, a third-generation perfumer, whose family holds 71.54%.
- A Delhi family firm that makes the scent in soaps and detergents. It mixes fragrances to order for consumer-product makers, and fragrance brought in ₹143.5 crore, 94.2% of FY26 revenue. The founding family listed it in June 2025 and still owns 71.54%.
- Sales and profit have grown fast, and it has no debt. In FY26 sales were ₹152.4 crore, up from ₹70.5 crore in FY23, and profit after tax was ₹28.4 crore. It has no borrowings, and the business brought in ₹26.1 crore of cash in FY26, so the profit is turning into cash.
- The old factory is full, and growth has slowed. Its only factory ran at about 124% of its capacity in FY26, by management's account. Sales in the second half of FY26 were ₹75.8 crore, 1% below the first half's ₹76.6 crore, and H1 FY27 revenue of ₹84.48 crore grew 10.34%, against 42% in FY26.
- The new plant is late, and the growth plan rests on it. The money raised at listing is building a ₹184 crore plant first promised for March 2026; trial production began in September 2026, 6 months late, with a new reason given at each delay. Management's target of ₹200 crore of revenue in FY27 needs that plant, and a ₹60 crore project loan sanctioned by HDFC Bank means the company is unlikely to stay debt-free.
- A few unnamed customers buy about half of what it sells. In FY25 the top 5 customers bought ₹53.0 crore, 49.3% of revenue, and none is on a long-term contract. No customer is named in any company document, and the FY26 investor presentation dropped the figure.
- The auditor left, and the paperwork keeps slipping. The auditor that signed the prospectus numbers resigned with immediate effect 7 weeks after listing, over a fee of ₹5.80 lakh against the ₹10 lakh it had proposed. The filings since carry wrong dates and figures that disagree: the promoter put research spending at "around 2.3%" of sales, while the annual report shows ₹20 lakh, 0.13% of revenue.
Why this company, why now
In FY26 Sacheerome reported ₹152.4 crore of revenue, up 42% and ₹28.4 crore of profit after tax, up 78%, with no debt (Balance sheet). On 13 October 2026 its business update put first-half FY27 growth at 10.34%, and the second plant had only just begun trial runs.
Sacheerome's share has more than doubled since September 2025
Sacheerome's closing share price on NSE Emerge, September 2025 to October 2026. It listed at ₹102 in June 2025, fell to ₹196 in September 2025, and climbed from there.

₹ per share, closing price
NSE end-of-day prices · 9 September 2025 to 9 October 2026
What the market believes. A small, debt-free, fast-growing manufacturer about to quadruple its capacity. The share listed at ₹153 against an IPO price of ₹102, fell after the auditor's resignation to ₹196 by 10 September 2025, and has since more than doubled, through the plant's delays and the slower half-year; the At a glance card above has today's price. Buyers and sellers are under Shareholding: the anchors left within a quarter; the family has sold nothing since listing. On 9 October 2026 67.86% of the shares traded were taken in delivery, on a thin day; selling a large holding quickly would move the price.
Where the filings differ. The old plant is past its rated capacity (Operations and capacity). The second plant reached trial production 6 months after the date in the prospectus, with a new reason at each delay, and has no licence and no named customer yet; the price is paying for its output before either exists. The paperwork keeps showing small cracks (Governance, safety and compliance). The questions are whether the next leg of growth arrives on time, whether the price already assumes it has, and how much weight to put on filings that disagree with each other.
History
Manoj Arora is a third-generation fragrance entrepreneur with 40 years in the industry, and still the chief perfumer. The company began in June 1992, took its present name in 2012, added flavours for confectionery, beverages and bakery in 2014, and was allotted the land for its second factory in 2020. His son Dhruv runs business development (Promoters).
- 1992 to 2012. Sacheerome Private Limited, a fragrance house in Okhla, built on the family's earlier businesses, on land owned by a family firm, Vaishali F&F LLP.
- March 2024. A bonus issue triples the share count (Shareholding).
The last 2 years are under Recent developments.
How the business works
How a Sacheerome scent is made, sold and reordered
Read top to bottom, from the ingredient supplier to the brand's reorder. The shaded steps are Sacheerome's own; the rest belong to its suppliers, its customers and the licences that gate the second plant.

Sacheerome prospectus, annual report FY26, results, call transcripts and business updates · FY25 and FY26
The chain starts with the ingredients: hundreds of aromatic chemicals, natural essential oils, oleoresins and resinoids, bought from Indian makers and importers, mostly in Maharashtra, the largest cost by far (Costs and inputs).
A consumer-product company writes a brief, who the product is for and what it should smell like, and the perfumers create a formula. The product becomes the customer's property; Sacheerome is "just the custodian", Manoj Arora said in November 2025. The brand tests it in the soap or the drink and approves it. The Okhla plant weighs and blends the compound (Operations and capacity), quality control tests the batch, and it ships by third-party transport. The brand rarely changes an approved smell (Competitive advantage).
Who holds the power: the customer, at the order. A handful of customers buy about half of what it sells, none on a long-term contract (Customers). Sacheerome's power is the formula and the switching cost (Competitive advantage). Why this matters: the margin lives in the formula, which costs little to make and much to replace, and the risk lives in 5 unnamed customers.
How the money is earned. Every product is a formula made to order and sold by the kilo. The fee is the price per kilo, with no royalty, service fee or add-on; revenue is volume times price times mix.
- Volume. Under Operations and capacity.
- Price. Revenue per kilo rose from about ₹1,230 in FY23 to about ₹1,450 in FY25, on the prospectus's production figures. Arora says prices were not raised; customers asked for better products.
- Mix. Fragrance against flavour, premium against commodity. Exports are a small share (Operations and capacity).
Who pays: the brand, about a month and a half after delivery (Working capital and cash flow).
Products and segments
The accounts report 1 segment, fragrances and flavours; the split is in the directors' report.
Fragrance, mostly. ₹143.5 crore of FY26 revenue, 94.2%: compounds for soaps, detergents, deodorants, hair and skin care, air care, candles and incense. Flavours were ₹8.7 crore, 5.7%, and scrap sales ₹21 lakh. Profit is not split by line; management says both earn similar margins.
Flavours against fragrance, over the years. Flavours have been the weaker line: 8.6% of revenue in FY23, down 20% to ₹5.2 crore in FY25, then back to ₹8.7 crore in FY26. Domestic against export is under Operations and capacity.
Fragrance earns the margin, by weight of revenue. Management is pushing both lines through the new plant, with 1 of its 2 towers for flavours alone and "premium" fragrances named in the growth strategy; the capital went into 1 building for both. Why this matters: the plan is more of the same fragrances for the same buyers, from a far bigger plant.
Customers
Consumer-product makers, FMCG companies and the makers of incense and detergent, in India and a little abroad. None is named in any company document.
Concentration. In FY25 the top 5 customers bought ₹53.0 crore, 49.3% of revenue, and the top 10 ₹62.5 crore, 58.2%, against 45.9% for the top 5 in FY23. None is on a long-term contract; orders come as quarterly, half-yearly or annual schedules. The H1 FY26 investor presentation had a slide with those concentration figures; the FY26 presentation dropped it, and the capacity utilisation slide, while keeping the line that reliance on top customers "is balanced with a well-diversified portfolio, reducing concentration risk". The FY26 annual report gives no top-customer figure.
Why they stay. The company says it has "not lost any business" in decades; why is under Competitive advantage, and where they are under Operations and capacity.
Bad debts and complaints. Receivables were ₹19.8 crore, ₹19.4 crore of them less than 6 months old, with no provision for doubtful debts; ₹13,000 was written off in FY26 against ₹35.4 lakh in FY25. No complaints disclosure (no BRSR).
Contracts and tenders. None, and no government customer.
Costs and inputs
₹60 of every ₹100 buys raw material. ₹19 is profit.
Every line is a share of FY26 revenue from operations. Gross margin has sat near 40% for 4 years; what widened the profit line is the ₹16 of overheads, which was ₹27 in FY23.

Sacheerome FY26 audited results and annual report · FY26
Of every ₹100 of FY26 sales, ₹60 bought materials, ₹8.4 paid staff, ₹7.5 went on other expenses, ₹1.6 on depreciation and ₹0.1 on interest, leaving ₹22.4 of operating profit before other income. Other income added ₹2.6, mostly deposit interest.
The inputs. Bought direct from the source or through Indian companies, planned on projections and past demand, with some materials bought to their cultivation cycles. Only ₹13 lakh was bought from abroad directly; the rest comes through Indian importers, so the rupee reaches it through suppliers' prices. Pass-through is under Pricing power.
The suppliers. By state, Maharashtra 54.7%, Uttar Pradesh 16.8%, Gujarat 9.9%, Karnataka 9.0% and Delhi 5.4% of FY25 purchases. The prospectus names no supplier and gives no top-10 share, but says the company depends on a limited number of suppliers for unique raw materials. Dues to small suppliers: ₹3.55 crore at March 2026; suppliers are paid faster than a year ago (Working capital and cash flow).
Fixed against variable. Materials move with volume; staff and other expenses barely moved as sales grew. Employee cost and other expenses together were ₹19.0 crore in FY23 and ₹24.3 crore in FY26 while revenue more than doubled, so as a share of sales 27.0% fell to 15.9%. Contract labour: 23 contractual staff against 158 on the rolls at the IPO.
Operating leverage. In FY26 alone other expenses rose 4% and employee cost 25%, far below the growth in revenue (Why this company, why now); a new plant adds fixed cost first.
Interest took 0.3% of pre-tax profit and tax 25.3%.
Pricing power
Gross margin has stayed within 2 points of 40% for 4 years while revenue per kilo rose by nearly a fifth (How the business works). Input costs rose with it and were passed on; Arora's account is that prices were not raised, customers asked for better, dearer products.
Who sets the price: the brand, per formula; Sacheerome's lever is the formula, which the brand cannot buy elsewhere. Price caps: none. Discounting: none on record; FY26's second half shows margin slipping, not price. Pass-through: the prospectus says the company has been able to pass on some increases. Asked in November for the contract terms and the lag, Arora gave no terms: "What in life does not have the fluctuation?"
Strong and weak halves. The second half of FY25 was 13% bigger than the first; the second half of FY26 was 1% smaller, because the plant was full. The filings disclose no seasonal pattern; soap and detergent are bought all year, and incense peaks around the festivals.
The cycle. Consumer staples, which is mild; the last downturn on record was the flavours line's fall in FY25 (Products and segments), recovered the next year.
Operations and capacity
The Okhla plant. On leased land in Okhla Industrial Area, Delhi, with an automated dispensing line imported from Europe, a power connection of 269 KVA and a laboratory with gas chromatographs and mass spectrometers. Capacity 7,60,000 kg a year; production was 7,40,560 kg in FY25, 97%, and about 124% in FY26 by management's account.
The YEIDA plant. A 21,250 square metre site on the Yamuna Expressway, adding 20 lakh kg for a combined 27.6 lakh kg, 3.6 times today's, though management has called it "5x (almost)" and "4x". Cost and funding: Capital allocation; contracts signed: Balance sheet.
Promised against delivered. Commercial operation in March 2026 in the prospectus, with machinery ordered by November 2025 and installed by December; "on track" in November; then 4 revisions: machinery dispatch and the project consultant in February; "ongoing global geopolitical conditions" in May; locally fabricated stainless steel on the June call, by when the machinery had "already come from Holland"; plant expected in August in the July update; "the delay from vendors" on 11 August and "the commissioning and electrical installations" on 29 August. Trial production began in September 2026.
Certificates. The business update lists IFRA, EU, FEMA, FSSAI and ISO 9001:2015. The Delhi Pollution Control Committee's consent to establish the Okhla plant, granted in 2000, "is not traceable". For YEIDA, CRISIL's reports since September 2025 say the consent to establish and the factory licence "will be obtained as and when needed".
Where the revenue is. 94% of FY26 revenue, ₹143 crore, was domestic. Exports grew 15% to ₹9.4 crore but fell from 7.6% of sales to 6.2%, because the company focused on the home market. The export markets in FY25 were the UAE, Bangladesh, Nigeria, Madagascar, Nepal and Mauritius, none above 2.4% of revenue. At home, Uttar Pradesh and Maharashtra took 59% of Indian sales in FY25, and Maharashtra's purchases nearly doubled from ₹13.4 crore the year before.
2 states buy 59% of what Sacheerome sells in India
Uttar Pradesh and Maharashtra took ₹58 crore of the ₹99 crore sold at home in FY25. The other 23 states and union territories that bought anything shared the rest.
₹ CRORE OF DOMESTIC REVENUE, FY25
- Uttar Pradesh₹32.2 cr 32.4%
- Maharashtra₹26.2 cr 26.4%
- Delhi₹11.1 cr 11.1%
- Himachal Pradesh₹6.8 cr 6.9%
- 23 other states and UTs₹23.0 cr 23.2%
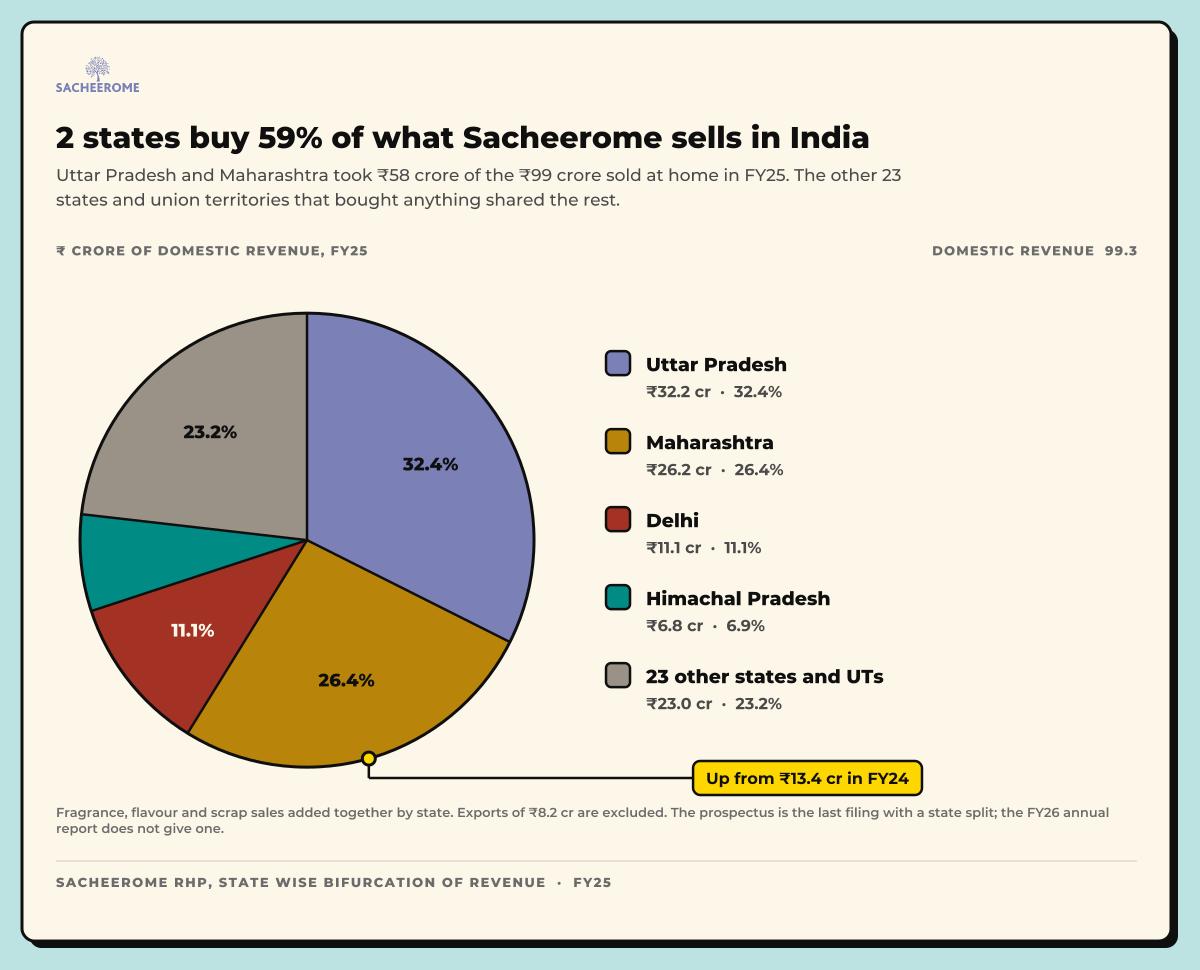
Up from ₹13.4 cr in FY24
Fragrance, flavour and scrap sales added together by state. Exports of ₹8.2 cr are excluded. The prospectus is the last filing with a state split; the FY26 annual report does not give one.
Sacheerome RHP, state wise bifurcation of revenue · FY25
Assets and staff are all in Delhi and, now, YEIDA in Uttar Pradesh. Currency is under Balance sheet.
Growth drivers and guidance
- Capacity. The old plant is past its rated output, and the new one more than triples it (Operations and capacity). Management guided to ₹200 crore of revenue in FY27, ₹250 crore in FY28 and ₹300 crore in FY29, growth of 31%, 25% and 20%, with ₹40 to 50 crore of FY27 from the new plant.
- Existing customers buying more. Of the ₹44.9 crore of revenue added in FY26, ₹31.2 crore came from existing customers.
- New customers. ₹13.6 crore in FY26.
- Exports. Named in every update; a small, shrinking share so far (Operations and capacity).
What is contracted: nothing. The first half of FY27 (Operating metrics and the last 8 quarters) shows what the business does without the new plant.
What management has promised for the next 1 to 3 years. The revenue path above; an EBIT margin held at about 25%, which Dhruv Arora confirmed means EBIT margin; and debt once the plant loan is drawn (Balance sheet).
The options, and their record so far.
- The new plant. In trial production since September 2026; the ₹300 crore of revenue by FY29 target uses the greater part of the combined capacity at today's price per kilo (Capital allocation).
- Pricing up. Revenue per kilo rose 18% in 2 years with no price increase, by selling dearer products; the new plant's R&D, application and consumer-evaluation centres are meant to sell more of those.
What has to go right: the plant must get its licences and run, the top customers must keep growing, and the fixed cost of the new building (Capital allocation) must be absorbed. The plant is real and running; the licences and the customers are not yet on record.
Competitive advantage
What stops a rival: the formulas, the relationships and the perfumer. A brand's fragrance is a trade secret held by its fragrance house; a rival must create something the brand likes better than a smell its customers already know. Arora has made them for a working lifetime (History).
The evidence: a gross margin that barely moved through 4 years of rising input costs (Pricing power); the claim that no customer has ever left (Customers); most of last year's growth from customers it already had (Growth drivers and guidance); a high return on equity even with idle cash (Return on capital).
The limits: it is personal, held by a 67-year-old perfumer and his son; it makes leaving inconvenient, not impossible; and it is not scale (Competitors and peers). How it erodes: a top customer takes its formula in-house or to a global house, which can match any formula and now sells AI-assisted design; a cheaper house undercuts on commodity compounds; the new plant's costs force cheaper products; or the succession does not carry the formulas with it.
Opening the rest…
Free account
Sign up for free to keep reading
A 6-digit code by email, no password. You also get The Macro Brew and The Edge Alert by email.
Already signed up? Use the same email to sign in.
Step 2 of 2
Check your email
Enter the 6-digit code sent to .
·